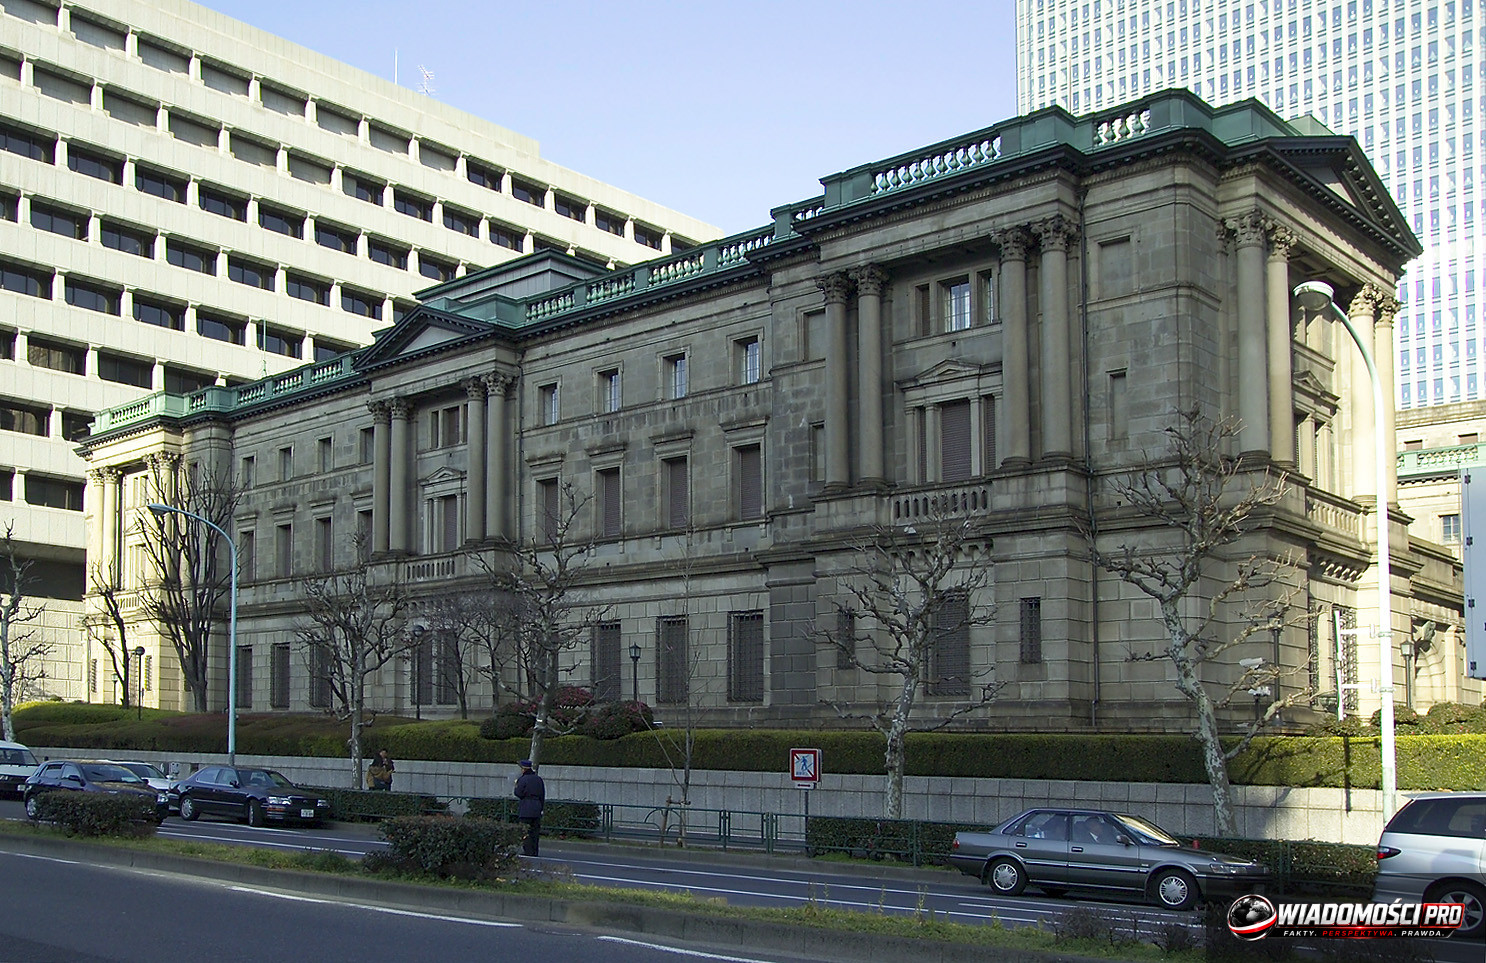
The yen is losing value as investors take profits after reaching the 1.25% level, and the market had priced in this decision well in advance. By raising interest rates to their highest level in 31 years, the Bank of Japan ended the longest period of negative or zero-interest rate policy in history; however, institutional players did not treat this as a signal to continue buying the yen. On the contrary, capital that had been accumulating the Japanese currency for months in anticipation of this move began massive withdrawals on Friday, September 18, 2026.
Historic rate hike: 1.25% after 31 years
The decision of September 18, 2026, marks a turning point in the Japanese economy. Raising rates to 1.25% is a move the financial markets have not seen in over three decades. For years, Japan functioned as a global hub for cheap money, financing carry trade operations around the world. Investors borrowed yen at zero cost to buy higher-yielding assets in the US or Europe. The policy change by the Bank of Japan (BoJ) was theoretically intended to end this process and lead to capital repatriation, which would have strengthened the yen.
The reality turned out to be different. The market stopped reacting to fundamentals the moment they were fully factored into futures contract prices. Hedge funds and investment banks, equipped with advanced forecasting models, had assumed a hike to 1.25% as early as the beginning of the third quarter of 2026. When the official BoJ statement confirmed these predictions, there was no surprise factor that could have fueled a further bull run for the Japanese currency.
From the perspective of economic theory, higher interest rates should increase a currency's attractiveness. In this case, however, stock market psychology took over. Investors who bought the yen in March or June treated the BoJ's decision as a target point. Reaching the 1.25% level served as a signal to close long positions and book profits. Capitalizing on the gains made in the period leading up to the decision became a priority, which naturally created selling pressure on the USD/JPY and GBP/JPY pairs.
The current situation puts the Bank of Japan in a difficult position. Governor Kazuo Ueda has declared his intention to continue the tightening cycle, but the market is becoming increasingly skeptical of his rhetoric. If subsequent macroeconomic data do not confirm that the Japanese economy can withstand higher credit costs without a drastic drop in consumption, the yen will remain under pressure. Investors no longer need assurances about "policy normalization." They need concrete evidence that the interest rate differential between Japan and the rest of the world will systematically narrow.
The "sell the fact" mechanism and the global capital game
The phenomenon of the yen sell-off after such a significant hike stems from the disparity between expectations and the speed of global capital's reaction. Institutional investors in 2026 operate with massive sums that cannot be withdrawn from the market in a matter of minutes. The process of positioning for the BoJ decision took months. When the official figure of 1.25% was released on September 18, the "sell the fact" mechanism kicked in with full force.
This situation is inextricably linked to the global macroeconomic environment. The US remains the main point of reference. Announcements regarding the maintenance of restrictive monetary policy in connection with Donald Trump's economic policy create a strong barrier to the yen's strengthening. US Treasury yields still offer a significantly higher return than their Japanese counterparts, even after the BoJ hike. Capital that could theoretically return to Japan finds no sufficient incentive there to abandon the safe haven of the dollar.
In Europe, the Bank of England and other central institutions remain highly cautious. Maintaining interest rates at current levels, while lacking abrupt moves from the BoE, means the yen is also losing strength against the pound. Investors watching the GBP/JPY pair clearly see that the lack of a decisive continuation of a hawkish course by the Bank of Japan after reaching 1.25% encourages a return to carry trade strategies. The market does not react to what central banks are doing today in nominal terms. The market reacts to how much their actions deviate from the American course.
The Tokyo Stock Exchange also felt this dissonance. Indices that had risen in anticipation of changes reacted with a nervous sell-off. Capital that had flowed into the stock market in search of benefits from a strengthening yen began to flee rapidly once it became clear that the BoJ did not intend to trigger a market shock. Liquidity was restricted, and volatility rose to levels usually seen during crisis periods. Investors closed "carry trade" orders en masse, which paradoxically weakened the yen even further, as closing these positions required buying back the funding currencies, and in this case, selling the yen was a part of balancing the books.
Kazuo Ueda's strategy in the face of turbulence
Kazuo Ueda is at a turning point. His statements following the announcement of the 1.25% hike suggest that the Bank of Japan has not yet said its last word. The BoJ Governor emphasizes that the era of ultra-loose policy has ended, which is a signal to global markets that Japan will move toward higher rates. The problem, however, is the credibility of these declarations in the eyes of investors who were "disappointed" by the lack of a more aggressive tone.
Ueda's strategy is based on gradually phasing out support for the economy while avoiding destabilization of the financial sector. It is a tightrope walk. Raising rates too quickly could lead to a collapse in the real estate market and declines on the stock exchange, which is already visible in the reaction of the Tokyo indices. Conversely, a pace that is too slow perpetuates the yen's weakness, which hits imports and increases cost-push inflation in Japan.
Analysts point out that after September 18, the market began to price the probability of another hike as marginal in the short term. It is precisely this lack of a prospect for quick, subsequent steps that is the main brake on the yen. If Ueda does not present a concrete schedule for further tightening in the coming weeks, the market will assume that the current 1.25% level is a ceiling for a long time. In such a scenario, the yen will lose value not because of Japan's weakness, but because of a lack of motivation to hold positions in that currency.
It is worth noting the behavior of Japanese government bonds. Long-term debt yields are not rising at a pace that would suggest investor conviction in a long-term cycle of hikes. The debt market is usually more precise than the currency market. If yields are not rising, it means the bond market does not believe in the Bank of Japan's aggressive path. This discrepancy between BoJ communication and debt pricing is one of the most significant signals for anyone managing capital based on Japanese assets.
Global context: Why is the yen losing the race for capital?
Analyzing the yen's situation requires a broader look at capital flows. In 2026, the global financial market is dominated by the search for yield with acceptable risk. Japan, despite the rate hike to 1.25%, still offers one of the lowest interest rate levels among developed economies. In a world where the US Federal Reserve maintains high rates, and the NBP and the Bank of England ensure the stability of their currencies, the yen struggles to attract large investment capital.
The reasons for this are multidimensional. First, the structure of Japanese public debt is so enormous that any interest rate hike drastically increases the cost of debt servicing for the state. The market is aware of the fiscal constraints facing Tokyo. Investors fear that the BoJ will be forced to intervene to support the bond market, which would negate the effects of the rate hikes.
Second, Japan's export sector, a pillar of the economy, is a beneficiary of a weak yen. A strong currency hits the margins of tech and automotive giants. There is, therefore, a tacit political consensus that the yen should not strengthen too quickly. Market players, knowing these dependencies, do not engage in long positions on the yen with the same determination as they do with currencies of countries whose central banks are openly fighting for the strength of their money.
Third, the issue of geopolitics. American economic policy under Trump, focused on protectionism and strengthening the dollar, acts as a vacuum for global capital. Investors prefer to hold dollars, even with the risk of political fluctuations in the US, rather than yen, which they perceive as a hostage to Japan's internal demographic and fiscal problems. Any attempt to flee from the dollar to the yen is suppressed by the market as soon as there is a shadow of a chance for a higher return in American debt instruments.
What this means for you: A concrete investment strategy
If you have exposure to the yen or are planning investments in Japanese assets, you must change your approach from "waiting for a trend" to "managing volatility." The current situation is not the time for aggressive yen buying in the hope of a quick return to an uptrend. The market shows that the 1.25% level is a price at which institutional capital prefers to exit the market rather than continue to take risks.
My investment recommendation is based on three pillars:
1. Reduce exposure to yen-based currency pairs. If you have long positions on USD/JPY or GBP/JPY, consider gradually closing them or hedging using "put" options, which will protect you from sudden drops in the event of a further yen sell-off. The volatility we observed on September 18 will not disappear in a few days. It will accompany every subsequent statement by Governor Ueda.
2. Diversify your portfolio toward higher-yielding instruments in other jurisdictions. Since the yen is losing its safe-haven status, there is no reason to keep an excessive portion of capital in it. Shifting some funds toward government bonds of countries with higher returns (e.g., the US or even selected emerging markets with a stable macro situation) will help mitigate the risk of a decline in the value of a yen-denominated portfolio.
3. Monitor the yield of 10-year Japanese Government Bonds (JGBs) as a key indicator. These, not the BoJ's communications themselves, will tell you when the market truly believes in further hikes. If JGB yields break through significant technical resistance without central bank intervention, it will be a signal that the debt market is forcing the BoJ to change policy. Until that happens, treat any rise in the yen after press conferences as an opportunity to exit positions, not to increase them.
Do not treat the yen as a speculative currency in the short term. Currently, it is an instrument used mainly for profit-taking by large funds. If you do not have sufficient liquidity and tools for currency risk management, the safest strategy is to observe from the sidelines until the USD/JPY rate stabilizes in a new price range, which should take 4 to 6 weeks.
Q&A
Is this the end of rate hikes in Japan?
No, Kazuo Ueda suggests further monetary policy tightening in his communications, which means the potential for further upward moves, although the pace of these changes remains an unknown for the market.
Why didn't the yen gain value after the hike?
The yen lost value because investors took profits after the currency's earlier appreciation before the decision, using the classic "buy the rumor, sell the fact" strategy, and the market had priced in the move to 1.25% long before the BoJ meeting.
How does the BoJ decision affect global markets?
The decision increases volatility on currency pairs and forces investors to re-evaluate 'carry trade' strategies, in which the yen was a cheap funding currency, which translates into capital outflows from Asian markets toward higher-yielding dollar assets.
Sources
- Historic rate hike in Japan. Yen loses significantly - Money.pl
- Rates in Japan at highest in 31 years. Surprising reaction of the yen and stock market - Bankier.pl
- Bank of Japan raises rates to highest level in 31 years - forexclub.pl
- Bank of Japan raised rates to levels from decades ago. Why did the yen lose instead of gain? - Comparic.pl
- Why did the Japanese yen lose value after the central bank raised interest rates to the highest level in 31 years? - Vietnam.vn
- GBP/JPY falls as BoE holds interest rates and yen strengthens ahead of Bank of Japan decision - VT Markets
- Interest rates are rising in Japan, what does this mean for investments? - Subiektywnie o finansach
- America will have higher rates because of Trump. NBP and Bank of England are also behaving rationally - Bankier.pl
Article prepared by the Wiadomości PRO editorial team with the support of artificial intelligence. Facts are derived from the sources listed above.

Komentarze (0)
Ładowanie komentarzy...