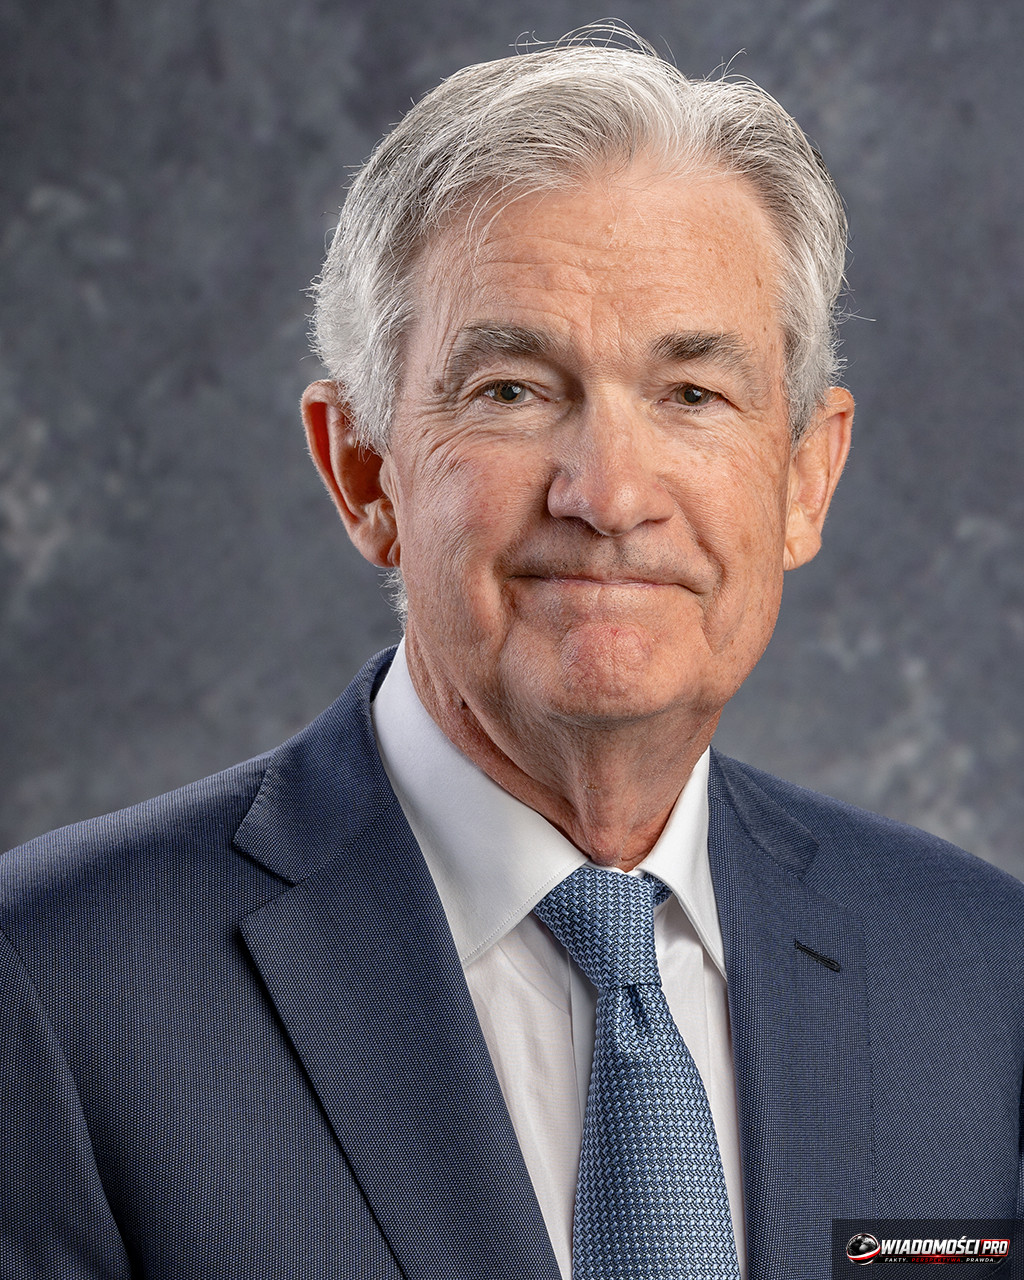
The Federal Reserve has lowered interest rates by 50 basis points to a range of 4.75-5.00%, which paves the way for cheaper financing, although real benefits for borrowers depend on the individual policies of commercial banks. No, loans will not become cheaper immediately, as financial institutions rarely pass on monetary decisions directly to their offers on the day the announcement is made. The process of transmitting monetary policy to the average debtor's wallet is intentionally drawn out over time to protect the interest margins of banks, which, in the face of a cycle change, are looking for ways to maintain their current profitability.
Decision mechanism: Why 50 basis points?
The decision made on September 16, 2026, ends a period of waiting that for months divided economists into supporters of rapid easing and defenders of a restrictive approach. Jerome Powell, Chair of the Federal Reserve, opted for a move deeper than the standard quarter of a percentage point, which is being read as an alarm signal regarding the condition of the American labor market. Instead of gradually withdrawing from high money costs, the Fed opted for an intervention intended to prevent the economy from cooling down too rapidly.
The American central bank does not operate in a vacuum. In recent quarters, macroeconomic data has become increasingly ambiguous. On one hand, persistent price pressure was observed, while on the other, private consumption began to show signs of exhaustion. The choice of 50 basis points is a compromise between fighting inflation and the fear of a recession, which in American realities could have consequences far worse than a temporary easing of policy.
For a person paying off a loan in the US, this move is the technical beginning of a decline in debt servicing costs. However, the mechanism through which this decision reaches the retail client is complicated. Commercial banks do not adjust their price lists automatically. Their pricing policy is based on forecasts regarding the future cost of interbank financing, not just the current FOMC decision. If a bank assesses that the coming months will bring instability, it will keep margins at a high level as long as competition allows.
Market reaction: Bonds and stock market turbulence
Investors, who in 2024 repeatedly experienced disappointment with Fed communication, this time received the concrete action they were waiting for. Despite this, the market did not react with a euphoric rally. The yield on US Treasury bonds, hovering around the 4.3% level, remains at the center of attention as a real barometer of the cost of money in the economy. It is worth noting that with such high yields, even a 50-basis-point cut in the short-term rate sector does not mean cheap debt for long-term investors.
The technology sector and growth-type companies, which suffered the most during the rate-hike cycle, followed Powell's conference with attention. Every mention of flexibility was analyzed in terms of future cash flows. The bond market, which often anticipates central bank decisions, had already priced in a similar move, meaning the surprise effect was limited. For the stock market, the trajectory of subsequent meetings is now more important than the cut itself.
If we compare the current situation with September 2024, a clear change in attitude is visible. Back then, the debate revolved around whether the Fed would even dare to cut, fearing persistent inflation. Today, in 2026, the discussion has shifted toward managing the risk of a slowdown. Stock market investors must now verify their portfolios in terms of companies whose balance sheets are most sensitive to interest rate levels. Over-indebted companies, which until now functioned by rolling over debt at a high cost, are finally receiving some margin of safety, but it is not a guarantee of success.
What about loans? Disappointment for bank clients
Let's translate this into concrete calculations. Suppose an American borrower has a mortgage worth $500,000 with a variable interest rate linked to the main rates. A 50-basis-point cut means a theoretical reduction in the annual interest cost of $2,500. However, in practice, commercial banks often do not pass the full cut on to the client, justifying it with the need to cover rising operating costs or credit risk.
Most bank clients will not feel this change in their household budget for the next three to six months. Financial institutions use transition periods in which the interest rates on credit products are updated with a delay. Banks operate in a model where profit from the interest margin is protected against a too-rapid decline in revenue. When rates fall, banks first lower the interest rates on deposits to maintain the spread, and only then do they reduce the costs of loans for their debtors.
Here are the barriers that effectively hinder a rapid drop in loan installments:
- Individual borrower risk assessment often outweighs the market trend. A bank may decide that despite lower rates, the macroeconomic situation increases the risk of default, which will prompt it to raise the margin, neutralizing the effect of the Fed's cut.
- The bank debt refinancing structure is based on futures contracts. A financial institution that has hedged against a drop in rates has no interest in quickly lowering the interest rates on its credit products, as its own cost of capital acquisition remains unchanged in the short term.
- Competition in the banking sector in the US is limited in many regions. Clients, having little choice, less frequently move their debt to other institutions, which gives banks room to adjust their offers to market conditions more slowly.
This process means that the enthusiasm associated with the central bank's decision often clashes with the cold calculation of bankers. For the individual client, this means that the real relief in the wallet will be deferred in time, and its scale will be smaller than the announcement from Washington would suggest.
Poland against the backdrop of the US: MPC vs. Fed
The decision to cut rates in the US stands in clear contrast to the actions of the National Bank of Poland (NBP). While in Washington the priority has become supporting a weakening labor market, in Warsaw the September 2024 MPC meeting ended with interest rates being kept at their current level. Polish policymakers remain hostages to internal inflation, which in our country shows completely different dynamics than across the ocean.
This is a divergence that has real consequences for the zloty. International capital reacts to differences in interest rate levels, which directly affects exchange rates. The Polish economy, being strongly linked to global supply chains, must face external pressure without having the same freedom of movement as the American Fed. Jerome Powell can afford aggressive stimulation, while the MPC must weigh the risk of inflation becoming permanently anchored in the Polish economy.
For a Polish borrower, following decisions from the US is instructive but does not translate directly into the cost of their debt. If our loan is in zlotys, it depends on the decisions of the MPC and WIBOR rates, which react to domestic CPI readings. The optimism flowing from the US is therefore a distant phenomenon that can only indirectly affect us through the exchange rate channel or sentiment on capital markets. Expecting that a decision from the US will force a move in Warsaw is a flawed assumption that ignores the fundamental differences in the mandate goals of both institutions.
Jerome Powell and the future of the cutting cycle
During the conference after the decision was announced, the Fed Chair was extremely cautious in making promises. Powell emphasized that every subsequent decision will be made based on incoming data, which in central banker language means no declaration whatsoever regarding the pace of future cuts. This approach, called *data-dependent*, is an attempt to avoid the mistake of the past, when easing policy too early led to a renewed jump in inflation.
The market must now get used to a state of uncertainty. Stopping the cutting cycle is just as likely as continuing it if labor market data turns out better than expected. Powell tried to balance the signals coming from the economy, ensuring that investors did not interpret the current move as the beginning of unlimited easing. Every month will now bring a new wave of speculation around subsequent FOMC meetings.
For borrowers who were counting on a quick return to the days of cheap financing, this is a warning signal. The era of cheap money will likely not return to the extent we remember from years ago. The new normal is interest rates that remain at levels higher than in the past decade, which forces greater financial discipline on consumers. Patience is the only strategy that has any economic justification in current conditions.
Summary: The investment landscape after the decision
The decision to cut rates is a signal that the American financial system is entering a new stage. For an investor, the most important lesson is understanding that the bond and stock market always discount the future. What happened today was largely expected by professional players, which is why a violent stock market reaction can be misleading. It is now crucial to look at how debt yields will change in the coming quarters.
Highly indebted companies that have been paying high interest can finally breathe, but their condition depends on whether the rate cut helps them improve cash flow or is a delayed reaction to an impending recession. Investors should remain highly cautious. Too much faith that 50 basis points will change the rules of the game in the real estate market or the financial sector can be costly.
Geopolitical uncertainty, high US public debt, and volatility in the commodities market are factors that the Fed must take into account. A rate cut is not a magic cure for all economic problems. It is rather a tool intended to prevent a collapse, not a guarantee of rapid growth. In investment portfolios, this means the necessity of diversification and avoiding the excessive enthusiasm that often accompanies central bank decisions.
What this means for you
As a consumer, you should look at Fed decisions through the prism of your own obligations. If you have a variable-rate loan, do not plan expenses based on an expected, quick reduction in your installment. Banks have their own internal procedures and rarely act at the pace that clients would expect. On the other hand, if you have savings in deposits, you must count on the fact that banks will lower their interest rates faster than they will in the case of loans. This is an asymmetry that is built into the business model of the banking sector.
It is also worth monitoring the announcements published on the Federal Reserve's websites, including the minutes from FOMC meetings. They contain detailed justifications for decisions, which often say more about the future intentions of bankers than short press notes. Understanding the decision-making process allows for better management of the household budget and avoiding hasty financial decisions that could result from an incomplete interpretation of signals coming from global markets.
Questions and answers
Does every Fed rate cut mean a drop in loan installments in Poland?
No. Fed decisions affect global financial markets, but loan installments in Poland depend on the decisions of the Monetary Policy Council and WIBOR rates, which reflect the situation in our economy, not in the US.
Why did the Fed decide on a 50-basis-point cut instead of the standard 25?
This scale of movement shows that central bankers deemed stronger support for the economy necessary, reacting to signals of a weakening labor market and the risk of the economy cooling down too much.
Where to look for reliable information about the Federal Reserve's next moves?
The most reliable source is the official announcements published by the Federal Reserve and the minutes from FOMC meetings, which shed light on the motivations of individual members of the decision-making committee.
Are commercial banks obligated to lower loan interest rates after a Fed move?
There is no mechanism that would legally force commercial banks to immediately lower the interest rates on credit products after a central bank decision. This is a sovereign business decision of each institution, resulting from its strategy for managing margins and risk.
Will the rate cut in the US affect the dollar exchange rate?
Interest rate decisions are one of the main factors shaping the value of a currency. Lower interest rates usually make a given currency less attractive to capital seeking higher returns, which can lead to a weakening of the dollar against other currencies, although this effect is often offset by other macroeconomic factors.
Is 4.75-5.00% the target range for rates in the US?
This is the range established as a result of the last decision, however, it is in no way final. Fed policy is flexible, and depending on incoming data on inflation and employment, this range may be further modified up or down at subsequent FOMC meetings.
Which sectors of the economy will feel the effects of the decision the fastest?
The fastest reactions are usually observed in the debt market and among technology companies, whose valuations are strongly correlated with interest rates. Subsequently, the impact of the decision will be visible in the financial and real estate sectors, where financing costs translate directly into companies' operating margins.
Sources
- Most bank clients will not be satisfied. There is an important decision - Business Insider Poland
- September Fed decision may disappoint stock markets. Debate around a possible interest rate cut in the US - Strefa Inwestorów
- Fed cuts interest rates sharply. Economists, however, were wrong - Bankier.pl
- Fed signals a halt to interest rate cuts, and US bond yields exceed 4.3%. - Vietnam.vn
- How will markets react if the Fed returns to rate cuts - analizy.pl
- MPC did not change interest rates in September '24 - Miesięcznik Finansowy BANK
- When will the Fed cut interest rates? There is an announcement from Jerome Powell - Rzeczpospolita
- The whole financial world was waiting for this decision. Americans decided what to do with rates - Interia Biznes
Article prepared by the Wiadomości PRO editorial team with the support of artificial intelligence. Facts come from the sources listed above.
Komentarze (0)
Ładowanie komentarzy...